Can I buy HSA-compatible health insurance through the Marketplace?

Key takeaways
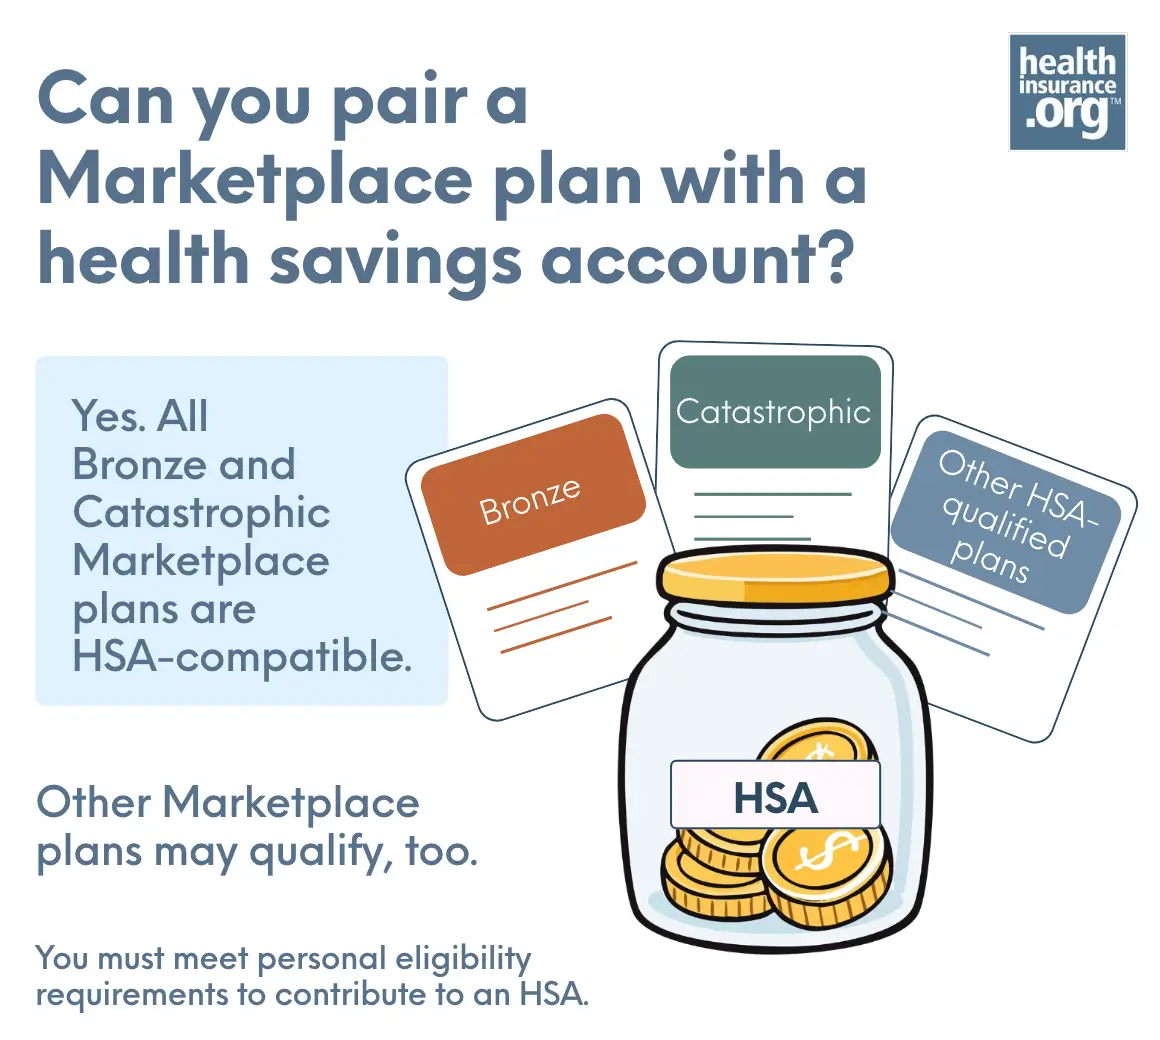
- All Bronze and Catastrophic Marketplace plans are HSA-compatible starting in 2026.
- HSA contributions are tax-deductible and can be withdrawn tax-free for qualified medical expenses.
- HSA contributions can reduce your ACA-specific income, potentially increasing your premium subsidy.
- Compare premiums, deductibles, provider networks and expected medical expenses before choosing an HSA-compatible plan.
Can I buy HSA-compatible coverage through the health insurance exchange in my state?
Yes. HSA-compatible health plans are available through the Marketplace in every state. Since 2026, all Bronze and Catastrophic Marketplace plans qualify, and some plans at other metal levels may qualify too.1 If you enroll in an HSA-compatible plan and meet HSA contribution eligibility requirements, you can set aside money with tax advantages to pay qualified medical expenses.
For freelancers, independent contractors and other gig workers, deductible HSA contributions can also reduce the annual household income used to determine Marketplace premium subsidies. That could mean a larger subsidy – or eligibility for one you otherwise wouldn’t receive.
When can I start contributing to an HSA?
You can choose an HSA-compatible plan during ACA open enrollment or a special enrollment period if you qualify. After you enroll in one of these plans, you can open a health savings account and make contributions, provided you meet the contribution eligibility requirements.
Am I eligible to contribute to an HSA?
To contribute pre-tax money to an HSA, you must sign up for a high-deductible health plan (HDHP). Other eligibility rules:2
- Have no other health coverage that disqualifies you.
- Not be enrolled in Medicare.
- Not be eligible to be claimed as someone else’s tax dependent.
If you combine gig work with another job, check whether coverage through that job – or a spouse’s plan – affects your HSA eligibility. Having multiple sources of income doesn’t disqualify you, but additional health coverage may.
How do plans qualify as HDHPs?
A plan is not an HDHP just because it has a high deductible; HDHPs also have to follow other rules laid out by the IRS, or they must be a Marketplace Bronze or Catastrophic plan. Here are the criteria for a plan to be an HDHP in 2027:
- It can be a Bronze or Catastrophic plan purchased in the health insurance Marketplace. These policies are all HDHPs, by definition, regardless of the plan design. (In other words, the IRS doesn't set specific rules for deductibles, out-of-pocket limits, or pre-deductible benefits for these policies.)
- If the policy isn't a Bronze or Catastrophic Marketplace plan, it must have a deductible of at least $1,750 for an individual or $3,500 for a family, and the out-of-pocket maximum can't be more than $8,700 for an individual or $17,400 for a family.3 (These limits are indexed each year by the IRS, and are lower than the out-of-pocket maximums that apply to non-HDHPs.) In addition, the policy must be designed so that it doesn't pay for anything other than preventive care before the minimum deductible is met. (So a policy with copays for office visits would fail to be an HDHP, even if it has a deductible and out-of-pocket maximum in the allowable range.)
 Recommendedhigh-deductible health plan (HDHP)
Where can I find an HDHP?
The good news is that the number of available Marketplace HDHPs greatly increased in 2026. HDHPs are now available through the Affordable Care Act's Marketplaces in all areas of the country, as all Marketplace Bronze and Catastrophic plans are considered HDHPs as of 2026.
CMS clarified that the average HealthCare.gov enrollee has access to 35 HSA-eligible plans for 2027.4
Depending on where you live, you might also see HDHPs at the Silver level5 (those plans would have to conform to the regular IRS rules for HDHPs, as discussed above).
How much can I contribute to an HSA?
If you're enrolled in an HDHP for 2026 (including a Bronze or Catastrophic plan purchased through the Marketplace in your state), you can contribute up to $4,400 if you have self-only HDHP coverage, or up to $8,750 if you have family HDHP coverage.6
If you enroll in an HDHP for 2027, the contribution limits are $4,500 if your HDHP covers just yourself, or $9,000 if it also covers at least one additional family member.3
If your gig income varies, consider how much you can comfortably contribute while keeping enough cash available for premiums and other bills. If you need the money for medical expenses during the year, you can withdraw it, tax-free. But if you withdraw money from your HSA for non-medical expenses, you’ll pay income tax and a penalty (assuming you’re not yet 65).
You don’t have to contribute the maximum allowable amount to your HSA. For 2027, if you have self-only HDHP coverage, you could contribute any amount between $0 and $4,500. And you can contribute it at any time during the year, or up until the tax filing deadline the following year. You can spread the contributions out across that time, or make your entire contribution in one lump sum on January 1, 2027, or April 15, 2028, or anytime in between.
Learn more about current HSA contribution limits, including catch-up contributions for people age 55 and older.
Get help from an expert who understands your needs
A licensed insurance agent can walk you through your options, explain costs and coverage, and help you enroll—all at no cost to you.
Footnotes
- “H.R.1 - One Big Beautiful Bill Act” (Section 71307). Congress.gov. Enacted July 4, 2025 ⤶
- “Publication 969 (2025), Health Savings Accounts and Other Tax-Favored Health Plans” IRS.gov. April 30, 2026. ⤶
- “Revenue Procedure 2026-24” Internal Revenue Service. Accessed Nov. 3, 2026 ⤶ ⤶
- “Plan Year 2027 Marketplace Plans and Prices Fact Sheet” Centers for Medicare & Medicaid Services. Oct. 30, 2026 ⤶
- “Health Insurance Exchange Public Use Files” (Plan Attributes PUF). Centers for Medicare & Medicaid Services. Accessed Jan. 7, 2026 ⤶
- “Revenue Procedure 2025-19” Internal Revenue Service. Accessed July 27, 2025 ⤶